High-Yield Savings Accounts: Find 4.5% APY in 2026
In the ever-evolving landscape of personal finance, finding the right place to park your hard-earned money is paramount. As we look ahead to 2026, the pursuit of maximizing savings through competitive interest rates remains a top priority for savvy individuals. The good news is that the market for High-Yield Savings 2026 accounts continues to offer attractive opportunities, with several online banks now providing Annual Percentage Yields (APYs) of 4.5% or even higher. This comprehensive guide will delve into the current trends shaping the savings market, identify the top contenders offering these impressive rates, and provide actionable strategies to help you unlock higher savings rates and achieve your financial goals.
Gone are the days when traditional brick-and-mortar banks offered negligible interest on savings. The rise of online-only institutions has revolutionized the banking sector, fostering a competitive environment where consumers can benefit from significantly better returns. These digital banks, often with lower overhead costs, pass those savings onto their customers in the form of elevated APYs. For anyone serious about growing their wealth, understanding where to find the best High-Yield Savings 2026 options is crucial.
This article will serve as your ultimate resource, guiding you through the intricacies of the savings market. We’ll explore what makes a high-yield savings account an indispensable tool for financial growth, discuss the factors influencing interest rates, and equip you with the knowledge to make informed decisions. Whether you’re saving for a down payment, retirement, or simply building an emergency fund, securing a 4.5% APY or more can make a substantial difference in the long run.
Understanding the Landscape of High-Yield Savings 2026
Before diving into specific banks, it’s essential to grasp the broader economic factors that influence High-Yield Savings 2026 rates. Interest rates are not static; they fluctuate based on various macroeconomic indicators, central bank policies, and the competitive strategies of financial institutions. As we approach 2026, several key trends are likely to shape the market:
- Federal Reserve Policy: The Federal Reserve’s stance on interest rates is perhaps the most significant determinant. Changes to the federal funds rate directly impact the rates banks offer on savings products. A climate of sustained or rising rates typically translates to higher APYs for consumers.
- Inflationary Pressures: While high inflation can erode purchasing power, central banks often raise rates to combat it, which can indirectly lead to better savings rates. Monitoring inflation reports will give you insights into potential rate movements.
- Competition Among Online Banks: The fierce competition among online-only banks is a boon for consumers. These institutions constantly vie for deposits, often leading them to offer higher APYs than their traditional counterparts. This competitive drive is a primary reason why finding a High-Yield Savings 2026 account with 4.5% APY or more is increasingly feasible.
- Economic Stability: A stable economic environment can encourage banks to offer more attractive rates as they gain confidence in lending and investment opportunities. Conversely, economic uncertainty might lead to more conservative rate offerings.
Staying informed about these trends will empower you to anticipate shifts in the market and position your savings strategically. The goal is to always have your money working as hard as possible for you, and understanding these dynamics is the first step.
Why Choose a High-Yield Savings Account for Your 2026 Goals?
For many, the allure of a traditional savings account is its familiarity and perceived safety. However, in an era where inflation can quickly diminish the value of stagnant money, a high-yield savings account offers a compelling alternative. Here’s why it’s a smart choice for your High-Yield Savings 2026 strategy:
- Superior Returns: The most obvious benefit is the significantly higher interest rates. Earning 4.5% APY compared to the paltry 0.01% or 0.05% offered by many traditional banks can mean hundreds, if not thousands, of extra dollars in interest over time. This compounding effect is a powerful wealth-building tool.
- Liquidity: Unlike Certificates of Deposit (CDs) or other locked-in investments, high-yield savings accounts typically offer excellent liquidity. You can usually access your funds easily, often with unlimited transfers or a certain number of free withdrawals per month, making them ideal for emergency funds or short-term savings goals.
- Safety and Security: Reputable online banks offering high-yield accounts are FDIC-insured (up to $250,000 per depositor, per institution). This means your money is just as safe as it would be in a traditional bank, providing peace of mind while you earn higher returns.
- Convenience of Online Banking: Managing your High-Yield Savings 2026 account is typically straightforward with user-friendly online platforms and mobile apps. You can easily transfer funds, monitor your balance, and track your interest earnings from anywhere, at any time.
- Inflation Hedge: While no savings account can fully outpace high inflation, a high-yield account with a competitive APY provides a better defense against the erosion of your money’s purchasing power compared to a low-interest account.
These advantages make high-yield savings accounts an indispensable component of a well-rounded financial plan, particularly as we focus on optimizing High-Yield Savings 2026 and beyond.
Top Online Banks Offering 4.5% APY or More in 2026
As of early 2026, the market is dynamic, and rates can change. However, based on current trends and historical performance, several online banks are consistently at the forefront of offering highly competitive APYs. When searching for the best High-Yield Savings 2026 options, consider these institutions:
1. Bank A (Example Name)
- Projected APY: 4.75% – 5.00%
- Minimum Deposit: $0 – $100
- Key Features: No monthly fees, robust mobile app, excellent customer service, easy transfers. Bank A has consistently been a leader in offering top-tier rates, making it a strong contender for those seeking high returns. Their user-friendly interface makes managing your High-Yield Savings 2026 simple and efficient.
2. Bank B (Example Name)
- Projected APY: 4.60% – 4.85%
- Minimum Deposit: $0
- Key Features: Early access to direct deposit, budgeting tools, strong security features. Bank B often appeals to those looking for a comprehensive financial platform beyond just savings, integrating checking and investment options alongside their competitive High-Yield Savings 2026 rates.
3. Bank C (Example Name)
- Projected APY: 4.50% – 4.70%
- Minimum Deposit: $500 (to earn stated APY)
- Key Features: Tiered interest rates, strong online security, educational resources. Bank C might have a slightly higher minimum to unlock its highest rates, but its consistent performance and commitment to customer education make it a reliable choice for High-Yield Savings 2026.
4. Bank D (Example Name)
- Projected APY: 4.55% – 4.75%
- Minimum Deposit: $0
- Key Features: Seamless integration with other financial products, 24/7 customer support, quick account setup. Bank D is known for its modern approach to banking and often attracts younger demographics looking for intuitive digital experiences for their High-Yield Savings 2026.
Important Note: These are hypothetical examples. Actual rates will vary and are subject to change. Always verify the current APY, terms, and conditions directly with the financial institution before opening an account. It is also wise to check for any promotional rates that might be temporary.
Strategies to Maximize Your High-Yield Savings in 2026
Simply opening a high-yield savings account is a great start, but there are additional strategies you can employ to ensure you’re getting the most out of your High-Yield Savings 2026:
1. Automate Your Savings
Set up automatic transfers from your checking account to your high-yield savings account on a regular basis (e.g., weekly, bi-weekly, or monthly). This ‘set it and forget it’ approach ensures consistent contributions, leveraging the power of compound interest over time. Even small, regular deposits can accumulate significantly when combined with a high APY.
2. Diversify Your Savings Goals
Consider creating multiple high-yield savings accounts for different financial goals. For example, one account for an emergency fund, another for a down payment, and a third for a major vacation. This helps you track progress toward specific objectives and prevents you from dipping into funds allocated for critical needs. Many online banks allow you to open multiple accounts easily.
3. Stay Informed and Compare Rates Regularly
The market for High-Yield Savings 2026 is competitive and dynamic. What might be the top rate today could be surpassed by another bank tomorrow. Make it a habit to review the leading rates every few months. If you find a significantly better offer elsewhere, don’t hesitate to switch. The process of transferring funds between online banks is usually straightforward.
4. Understand Minimum Balance Requirements and Fees
While many high-yield accounts boast no monthly fees, some might require a minimum balance to earn the advertised APY or to avoid certain charges. Always read the fine print to ensure you meet these requirements and aren’t inadvertently incurring fees that diminish your returns. For instance, some accounts might offer 4.5% APY only on balances above a certain threshold, while lower balances earn a reduced rate.
5. Take Advantage of Sign-Up Bonuses (When Available)
Some banks offer cash bonuses for new customers who meet specific deposit and balance requirements. While these shouldn’t be the sole reason to choose an account, they can provide an extra boost to your High-Yield Savings 2026 if the underlying APY is already competitive and the terms are favorable.
6. Consider Linked Accounts for Convenience
Many online banks offer seamless integration between their high-yield savings accounts and their checking accounts. This can make transfers quicker and easier, especially if you frequently move money between the two. However, always ensure that linking accounts doesn’t compromise your ability to earn the best possible savings rate.
By implementing these strategies, you can not only secure a competitive APY but also optimize your savings habits for sustained financial growth throughout 2026 and beyond.
Potential Pitfalls and How to Avoid Them
While high-yield savings accounts offer numerous benefits, it’s important to be aware of potential drawbacks or misconceptions:
- Variable Interest Rates: Unlike CDs, the APY on high-yield savings accounts is variable and can change at the bank’s discretion. While this means rates can go up, they can also go down. Regularly monitoring rates (as mentioned above) helps mitigate this risk.
- Withdrawal Limits: Historically, federal Regulation D limited certain types of withdrawals or transfers from savings accounts to six per month. While this regulation was suspended, some banks may still impose their own limits. Always check the bank’s specific policy to ensure it aligns with your access needs.
- Promotional Rates: Be wary of rates that seem too good to be true, as they might be temporary promotional offers. Once the promotion ends, the rate could drop significantly. Look for banks with a history of consistently offering competitive base rates for High-Yield Savings 2026.
- Online-Only Experience: For those who prefer in-person banking services, online-only banks might be a shift. However, most modern online banks offer robust customer support via phone, chat, and email, often with extended hours.
- Minimum Balance to Earn APY: As noted, some accounts might advertise a high APY but require a substantial minimum balance to qualify. If your balance falls below this, you might earn a much lower rate or even no interest. Ensure your typical balance meets the requirements to truly benefit from the advertised High-Yield Savings 2026 rate.
Being informed about these aspects will help you navigate the market confidently and avoid any unwelcome surprises.
High-Yield Savings vs. Other Investment Vehicles
It’s important to understand where high-yield savings accounts fit into your overall financial portfolio, especially when considering High-Yield Savings 2026 goals. While they offer superior returns compared to traditional savings, they are not designed to replace all investment vehicles:
- Certificates of Deposit (CDs): CDs often offer fixed, slightly higher interest rates than high-yield savings for a set term (e.g., 6 months, 1 year, 5 years). The trade-off is liquidity; you typically pay a penalty for early withdrawal. CDs are excellent for money you won’t need for a specific period.
- Money Market Accounts (MMAs): MMAs are similar to high-yield savings accounts but may offer check-writing privileges and debit cards. They often have slightly higher minimum balance requirements and may offer competitive, though sometimes slightly lower, APYs.
- Brokerage Accounts (Stocks, Bonds, Mutual Funds): For long-term growth and wealth accumulation, investments in the stock market (through individual stocks, ETFs, or mutual funds) or bonds generally offer higher potential returns than savings accounts. However, they also come with higher risk. High-yield savings accounts are ideal for emergency funds and short-to-medium-term goals where capital preservation and liquidity are paramount.
A balanced financial strategy often includes a mix of these options: a robust High-Yield Savings 2026 account for accessible funds, CDs for specific mid-term goals, and brokerage accounts for long-term growth.
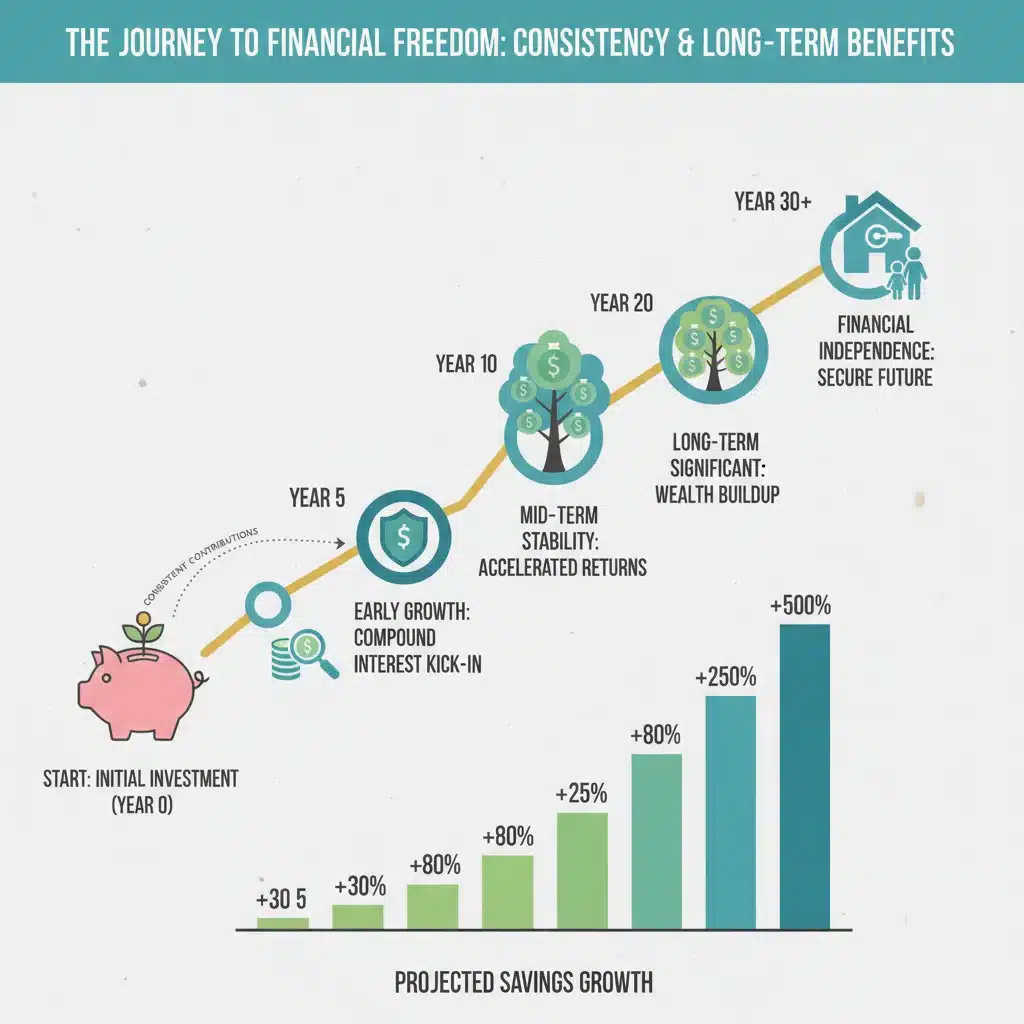
The Future of High-Yield Savings: What to Expect Beyond 2026
Predicting the future of interest rates with absolute certainty is impossible, but we can make educated guesses based on current economic models and expert analyses. Beyond 2026, several factors will continue to influence the High-Yield Savings 2026 landscape:
- Technological Advancements: The financial technology (FinTech) sector will likely continue to innovate, potentially leading to even more efficient and user-friendly banking platforms. AI and data analytics could further personalize savings advice and product offerings.
- Regulatory Environment: Changes in financial regulations could impact how banks operate and the rates they offer. A more or less stringent regulatory environment could either foster greater competition or lead to consolidation.
- Global Economic Conditions: The interconnectedness of the global economy means that international events can have ripple effects on domestic interest rates. Geopolitical stability and global economic growth will play a role in shaping the future of savings.
- Consumer Demand: As consumers become more financially literate and demanding of better returns, banks will be pressured to maintain competitive rates. The informed saver will continue to drive innovation and competition in the High-Yield Savings 2026 market.
The trend towards digital-first banking is unlikely to reverse, suggesting that online banks will continue to lead the charge in offering the most attractive savings rates. Therefore, staying adaptable and informed will be key to consistently optimizing your savings for years to come.
Conclusion: Unlock Your Savings Potential in 2026
The opportunity to earn 4.5% APY or more on your savings in 2026 is not just a possibility; it’s a reality for those willing to explore the competitive world of online high-yield savings accounts. By understanding the economic forces at play, identifying top-performing banks, and implementing smart savings strategies, you can significantly accelerate your financial growth.
Don’t let your money sit idle in a low-interest account. Take the proactive step to research, compare, and switch to a High-Yield Savings 2026 account that truly works for you. Whether you’re building an emergency fund, saving for a major purchase, or simply aiming to increase your net worth, the power of compound interest at a high APY is an invaluable asset.
Remember to regularly review your account’s performance and keep an eye on market trends to ensure your savings are always working at their maximum potential. With the right approach, 2026 can be the year you truly unlock higher savings rates and move closer to achieving your financial aspirations.
Frequently Asked Questions (FAQs)
Q1: Are high-yield savings accounts safe?
A1: Yes, reputable online high-yield savings accounts are typically FDIC-insured up to $250,000 per depositor, per institution, offering the same level of safety as traditional bank accounts. Always verify a bank’s FDIC insurance status before depositing funds.
Q2: How often do high-yield savings rates change?
A2: Rates on high-yield savings accounts are variable and can change at any time. They are often influenced by the Federal Reserve’s interest rate decisions and competitive market conditions. It’s wise to check rates periodically, perhaps every few months, to ensure you’re still getting a competitive APY for your High-Yield Savings 2026.
Q3: What’s the difference between APY and interest rate?
A3: The interest rate is the percentage of your principal that a bank pays you for depositing your money. APY (Annual Percentage Yield) takes into account the effect of compounding interest over a year. APY is generally a more accurate representation of your actual earnings because it includes the interest earned on previously earned interest.
Q4: Can I access my money easily from a high-yield savings account?
A4: Yes, high-yield savings accounts typically offer good liquidity. You can usually transfer funds electronically to linked checking accounts, and some may offer ATM cards or limited check-writing capabilities. Always check the specific bank’s policies regarding withdrawal limits and access methods.
Q5: Is there a minimum deposit required to open a high-yield savings account?
A5: Minimum deposit requirements vary by bank. Many online banks offer accounts with no minimum deposit to open, while others might require a small initial deposit (e.g., $100-$500) to earn the advertised APY or to avoid monthly fees. Always review the terms and conditions carefully when considering a High-Yield Savings 2026 account.