Debt Repayment Strategies 2026: Accelerate Financial Freedom by Reducing Consumer Debt
Debt Repayment Strategies 2026: Accelerate Financial Freedom by Reducing Consumer Debt
Are you ready to take control of your financial future? As we look ahead to 2026, many individuals and families are grappling with consumer debt, feeling the weight of credit card balances, personal loans, and other financial obligations. The good news is that achieving financial freedom is not just a dream; it’s an attainable goal with the right approach and consistent effort. This comprehensive guide will walk you through effective debt repayment strategies designed to help you reduce your consumer debt by a significant 15% this year, paving the way for a more secure and prosperous financial life.
Consumer debt can be a formidable adversary, often accumulating slowly but growing relentlessly with interest. It can impact everything from your mental well-being to your ability to achieve significant life milestones like buying a home or saving for retirement. Understanding the scope of your debt and developing a clear, actionable plan is the first crucial step towards overcoming it. This article focuses on practical, real-world strategies that you can implement starting today to make a tangible difference in your debt repayment journey.
We’ll delve into various methodologies, from creating a robust budget to choosing the best repayment method for your situation, exploring negotiation tactics, and leveraging technology. Our aim is to empower you with the knowledge and tools necessary to not only reduce your debt but also to build sustainable financial habits that will serve you well for years to come. Let’s embark on this journey to financial freedom together, armed with the best debt repayment strategies for 2026.
Understanding Your Debt Landscape: The First Step to Freedom
Before you can effectively tackle your debt, you need to understand it thoroughly. This means knowing exactly how much you owe, to whom, at what interest rates, and what the minimum payments are. Many people avoid confronting these numbers, but knowledge is power in this context. Gathering all your debt information is the foundational element of any successful debt repayment strategies.
Compile All Debt Information
- Credit Cards: List each card, its balance, interest rate (APR), and minimum monthly payment.
- Personal Loans: Note the original loan amount, current balance, interest rate, and monthly payment.
- Auto Loans: Track the remaining balance, interest rate, and monthly payment.
- Student Loans: Differentiate between federal and private loans, noting balances, interest rates, and payment schedules.
- Medical Debt: Understand the amounts owed and any payment plans in place.
- Other Debts: Include any other forms of consumer debt, such as payday loans or lines of credit.
Once you have this comprehensive list, you can create a debt summary spreadsheet or use a financial tracking app. This visual representation will help you see the full picture and identify high-interest debts that should be prioritized. High-interest debt is often the most insidious, as it grows quickly and can significantly hinder your progress. Identifying these accounts is a critical component of effective debt repayment strategies.
Creating a Bulletproof Budget: Your Financial GPS
A budget is not about restriction; it’s about control. It’s your roadmap to understanding where your money goes and how you can allocate it more effectively towards debt repayment. A well-constructed budget is indispensable among all debt repayment strategies.
Track Your Income and Expenses
Start by tracking every dollar that comes in and goes out for at least one month. This will give you an accurate picture of your spending habits. Many people are surprised to find out how much they spend on non-essentials. Categories to track include:
- Fixed Expenses: Rent/mortgage, loan payments, insurance premiums.
- Variable Expenses: Groceries, utilities, transportation, entertainment, dining out.
- Discretionary Spending: Hobbies, shopping, subscriptions.
Identify Areas for Savings
Once you have a clear understanding of your spending, look for areas where you can cut back. Even small reductions can add up over time and free up more money for debt repayment. Consider:
- Reducing discretionary spending: Can you cut down on eating out, subscription services, or impulse purchases?
- Negotiating bills: Call your internet, cable, and insurance providers to see if you can get a better rate.
- Lowering utility costs: Be more mindful of energy consumption at home.
- Finding cheaper alternatives: Opt for generic brands, pack your lunch, or carpool.
The money saved from these adjustments can be directly applied to your debt, accelerating your repayment timeline. This reallocation of funds is a cornerstone of successful debt repayment strategies.
Choosing Your Battle Plan: Debt Snowball vs. Debt Avalanche
When it comes to accelerating debt repayment, two popular and highly effective methods stand out: the debt snowball and the debt avalanche. Both are excellent debt repayment strategies, but they cater to different psychological and financial preferences.
The Debt Snowball Method
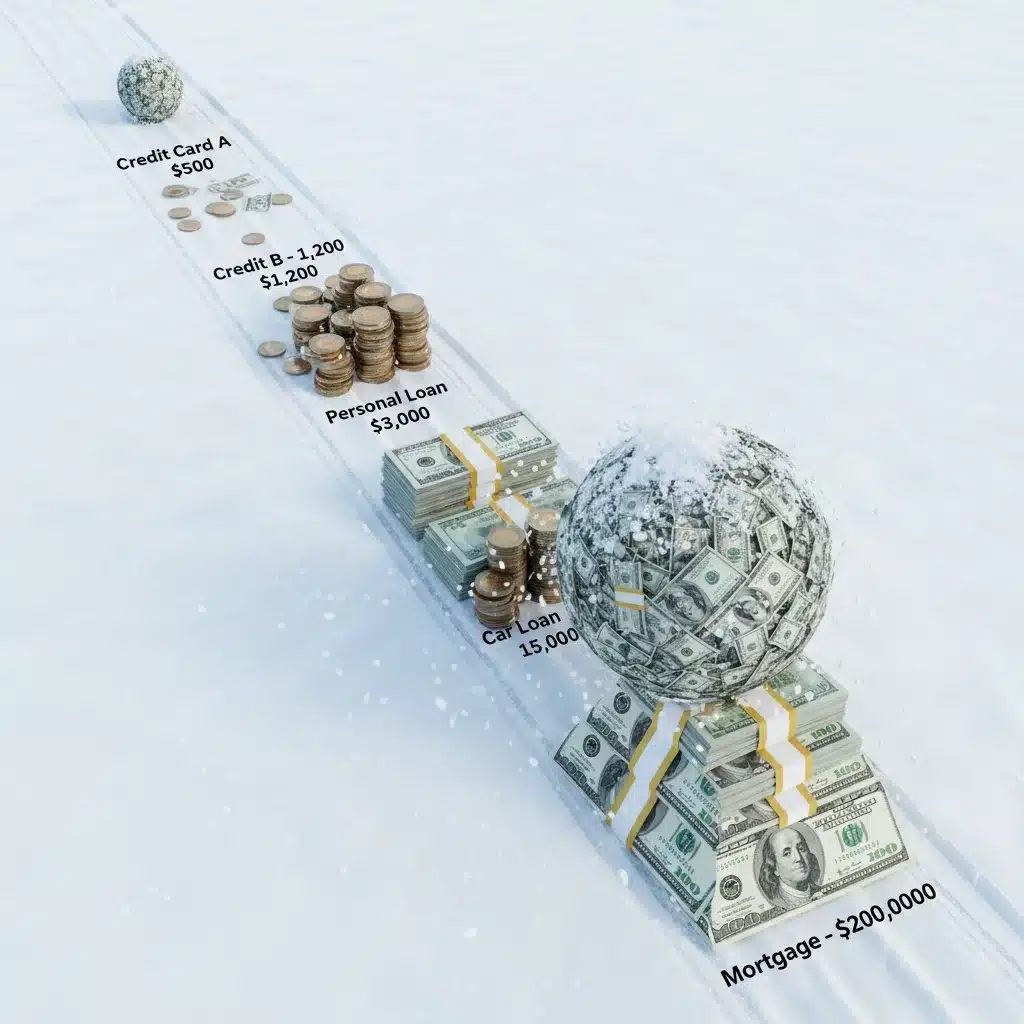
The debt snowball method prioritizes paying off your smallest debt first, regardless of the interest rate, while making minimum payments on all other debts. Once the smallest debt is paid off, you take the money you were paying on that debt and add it to the minimum payment of the next smallest debt. This creates a ‘snowball’ effect, where your payments grow larger as each debt is eliminated.
Pros:
- Psychological Wins: Paying off entire debts quickly provides powerful motivation and a sense of accomplishment.
- Momentum: The rapid succession of paying off debts builds momentum, making it easier to stick to the plan.
Cons:
- More Interest Paid: You may end up paying more interest over the long run because you’re not prioritizing high-interest debts.
This method is ideal for individuals who need quick wins to stay motivated on their debt repayment journey. It’s a powerful psychological tool among the various debt repayment strategies.
The Debt Avalanche Method
The debt avalanche method prioritizes paying off the debt with the highest interest rate first, while making minimum payments on all other debts. Once the highest-interest debt is paid off, you apply that payment amount to the debt with the next highest interest rate, and so on.
Pros:
- Saves Money: By attacking the highest interest rates first, you minimize the total amount of interest paid over the life of your debt.
- Faster Repayment: Mathematically, this method leads to the fastest overall debt repayment.
Cons:
- Less Immediate Gratification: If your highest-interest debt is also your largest, it might take a while to pay it off, potentially leading to demotivation.
The debt avalanche is best for those who are highly disciplined and focused on the mathematical efficiency of their debt repayment strategies.
Choose the method that best aligns with your personality and financial discipline. The most effective strategy is the one you can stick with consistently.
Boosting Your Income: More Fuel for Debt Repayment
While cutting expenses is vital, increasing your income can significantly accelerate your debt repayment. This is another powerful tool in your arsenal of debt repayment strategies.
Explore Side Gigs and Freelancing
In today’s gig economy, there are numerous opportunities to earn extra income. Consider:
- Freelance work: Writing, graphic design, web development, virtual assistant services.
- Delivery services: Food delivery, grocery shopping.
- Ridesharing: Driving for ride-sharing apps.
- Selling items: Declutter your home and sell unused items online or at local markets.
- Pet sitting/dog walking: Offer services to neighbors and friends.
Every extra dollar earned can be directly applied to your highest-priority debt, dramatically shortening your repayment timeline and reducing the total interest paid.
Negotiate a Raise or Seek Promotion
If you’re employed, consider whether you’re due for a raise or promotion. Prepare a strong case highlighting your contributions and market value. A higher salary can provide a consistent boost to your debt repayment efforts, making it one of the most impactful debt repayment strategies.
Leveraging Debt Consolidation and Refinancing
For some, consolidating or refinancing debt can be a game-changer. These are advanced debt repayment strategies that can simplify your payments and potentially lower your interest rates.
Debt Consolidation Loan
A debt consolidation loan allows you to combine multiple debts into a single, new loan, often with a lower interest rate and a single monthly payment. This can simplify your finances and reduce the overall interest you pay.
Considerations:
- Interest Rate: Ensure the new loan’s interest rate is significantly lower than your current average.
- Fees: Be aware of any origination fees or other charges associated with the new loan.
- Discipline: While consolidation simplifies payments, it doesn’t solve underlying spending habits. You must commit to not incurring new debt.
Balance Transfer Credit Cards
If you have high-interest credit card debt, a balance transfer credit card with a 0% introductory APR can be a powerful tool. You transfer your existing balances to the new card and have a period (e.g., 12-18 months) to pay it off interest-free.
Considerations:
- Transfer Fees: Most balance transfers come with a fee, typically 3-5% of the transferred amount.
- Introductory Period: Be sure you can pay off the transferred balance before the introductory period ends and the regular APR kicks in.
- Credit Score: You’ll generally need a good credit score to qualify for the best balance transfer offers.
Refinancing Student Loans or Mortgages
If you have student loans or a mortgage, refinancing could lead to a lower interest rate or a more manageable monthly payment. However, carefully weigh the pros and cons, as refinancing can sometimes extend the loan term, potentially increasing the total interest paid over time.
Negotiating with Creditors: Don’t Be Afraid to Ask
Many people don’t realize that creditors are often willing to work with you, especially if you’re proactive and honest about your financial situation. This can be a highly effective, though sometimes intimidating, aspect of debt repayment strategies.
Lower Interest Rates
Call your credit card companies and ask if they can lower your interest rate. Explain your commitment to paying off your debt and your current financial challenges. Even a few percentage points can make a significant difference over time.
Payment Plans and Hardship Programs
If you’re struggling to make minimum payments, contact your creditors immediately. They may offer hardship programs, reduced payment plans, or temporary forbearance. Ignoring the problem will only make it worse, leading to late fees and negative impacts on your credit score.
Debt Settlement (Use with Caution)
Debt settlement involves negotiating with creditors to pay a lump sum that is less than the total amount you owe. While it can reduce your debt, it often comes with significant negative consequences for your credit score and can have tax implications. This should generally be a last resort and explored with the guidance of a reputable credit counseling agency.
Building an Emergency Fund: Your Financial Safety Net
It might seem counterintuitive to save money while trying to pay off debt, but an emergency fund is a critical component of long-term financial stability and effective debt repayment strategies. An emergency fund prevents you from incurring new debt when unexpected expenses arise.
Start Small
Aim for a mini-emergency fund of $1,000 to $2,000 initially. This can cover minor emergencies like car repairs, medical co-pays, or unexpected home maintenance issues without having to rely on credit cards.
Automate Savings
Set up automatic transfers from your checking account to a separate savings account each payday. Even small, consistent contributions will grow over time. Once your high-interest debt is paid off, you can then focus on building a more substantial emergency fund, typically 3-6 months’ worth of living expenses.
Leveraging Technology for Debt Repayment
In 2026, technology offers an array of tools to help you manage and repay your debt more efficiently. Integrating these tools into your financial routine can significantly enhance your debt repayment strategies.
Budgeting Apps
Apps like Mint, YNAB (You Need A Budget), Personal Capital, and EveryDollar can help you track spending, categorize expenses, and set budget goals. Many integrate directly with your bank accounts for seamless tracking.
Debt Management Apps
Some apps are specifically designed for debt repayment, allowing you to input your debts and visualize your progress using either the snowball or avalanche method. They can forecast repayment dates and suggest optimal payment strategies.
Automation and Reminders
Set up automatic payments for your minimums to avoid late fees. Use calendar reminders or app notifications for extra payments you plan to make. Consistency is key, and technology can help you stay on track.
Maintaining Momentum and Staying Motivated
Debt repayment is a marathon, not a sprint. There will be good days and challenging days. Maintaining motivation is crucial for the long-term success of your debt repayment strategies.
Celebrate Small Wins
Acknowledge and celebrate every milestone, no matter how small. Paid off a credit card? Reduced your total debt by 5%? Treat yourself to a small, non-financial reward, like a favorite meal cooked at home or a relaxing evening.
Track Your Progress Visually
Create a visual tracker – a spreadsheet, a chart, or even a physical thermometer – to see your debt decreasing. Watching the numbers go down can be incredibly motivating.
Find an Accountability Partner
Share your goals with a trusted friend, family member, or join an online community. Having someone to share your successes and challenges with can provide valuable support and keep you accountable.
Educate Yourself Continuously
Keep learning about personal finance. Read books, listen to podcasts, and follow financial experts. The more knowledgeable you become, the more confident you’ll be in managing your money and implementing effective debt repayment strategies.
Avoiding Future Debt: Building Sustainable Habits
Paying off debt is only half the battle; the other half is staying out of it. Developing sustainable financial habits is paramount for long-term financial freedom.
Live Below Your Means
Make a conscious effort to spend less than you earn. This fundamental principle of personal finance is key to building wealth and avoiding future debt.
Pay with Cash or Debit
If credit cards are a major source of your debt, consider switching to cash or debit for everyday purchases. This can help you stay within your budget and avoid accumulating new balances.
Think Before You Buy
Implement a ‘waiting period’ for non-essential purchases. If you still want the item after 24-48 hours, then consider buying it. This helps curb impulse spending.
Regular Financial Reviews
Schedule monthly or quarterly financial reviews to assess your progress, adjust your budget, and ensure you’re still on track with your goals. These reviews are essential for refining your debt repayment strategies and ensuring their continued effectiveness.
The Role of Professional Help: When to Seek Guidance
While this guide provides a wealth of debt repayment strategies, some situations may warrant professional assistance. Don’t hesitate to seek help if you feel overwhelmed or stuck.
Non-Profit Credit Counseling
Non-profit credit counseling agencies offer free or low-cost services to help you create a budget, develop a debt management plan (DMP), and negotiate with creditors. They can provide unbiased advice and support.
Financial Advisors
For more complex financial situations, including investment planning alongside debt repayment, a certified financial advisor can provide personalized guidance.
Bankruptcy (Last Resort)
Bankruptcy should always be considered a last resort, as it has severe and long-lasting consequences for your credit and financial future. However, in extreme cases of insurmountable debt, it may be the only viable option. Consult with a bankruptcy attorney to understand the implications.
Conclusion: Your Path to 15% Debt Reduction and Beyond
Reducing your consumer debt by 15% in 2026 is an ambitious yet entirely achievable goal. By diligently applying these debt repayment strategies – understanding your debt, creating a stringent budget, choosing the right repayment method, boosting your income, leveraging consolidation, negotiating with creditors, building an emergency fund, and utilizing technology – you can make significant strides towards financial freedom.
Remember that consistency, discipline, and patience are your greatest allies. There will be setbacks, but every small step forward contributes to your overall success. Embrace the journey, celebrate your progress, and commit to building a financially stable future. The power to transform your financial life is within your grasp. Start implementing these strategies today and witness the profound impact they have on your journey to becoming debt-free.